30 Oct

Bank of Canada Raises Interest Rates: What Does This Mean for Canadian Homeowners and Buyers?

General

Posted by: Livian Smith

October 30, 2026 | By Livian Smith, Mortgage Broker
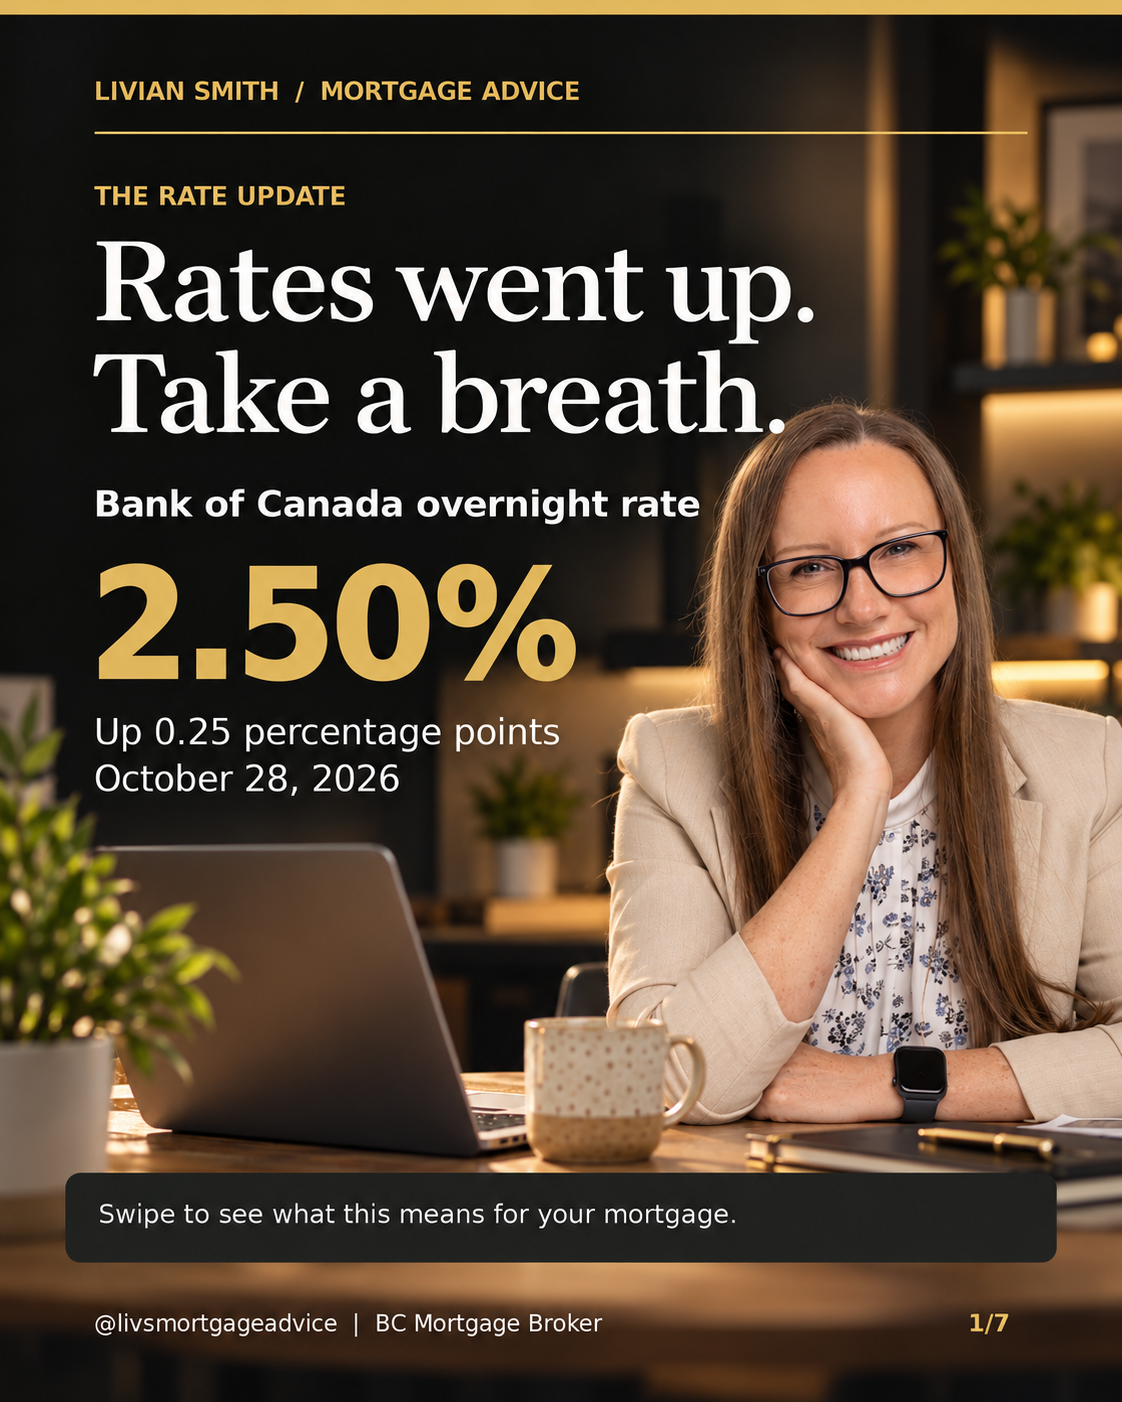
 

The Bank of Canada has raised its overnight lending rate by 0.25%, bringing it to 2.50% following its October 28, 2026 announcement.

For Canadians with variable-rate mortgages, those approaching renewal, or anyone considering purchasing a home, this news may have raised a few concerns.

But before making any decisions about your mortgage, it’s important to understand why rates increased, what economists are saying, and what this could mean for your financial future.

The good news? A rate increase doesn’t automatically mean it’s time to panic or change your mortgage strategy.

Let’s look at the bigger picture.

Why Did the Bank of Canada Raise Interest Rates?

According to the Bank of Canada’s October 28 announcement, the decision to increase rates was largely influenced by persistent inflation and rising energy costs.

While higher interest rates can create challenges for borrowers, the Bank of Canada is attempting to prevent rising energy prices from spreading further into the cost of everyday goods and services.

Here are some of the key economic highlights reported following the announcement:

  • Economic growth remains resilient. Canada’s GDP grew by 3.3% in the second quarter, exceeding the Bank of Canada’s expectations.
  • Inflation remains a concern. Consumer price inflation has been hovering around 3%, with projections suggesting it could reach approximately 3.5% by the end of 2026.
  • Consumer spending remains relatively strong. Despite economic uncertainty, Canadians continue to contribute to economic growth.
  • Housing affordability remains challenging. Higher borrowing costs, construction expenses, and slower population growth are expected to influence housing activity over the coming years.

The important takeaway is that the Bank of Canada is responding to economic conditions, not necessarily signalling the beginning of another prolonged cycle of interest rate increases.

However, future decisions will depend on inflation, employment, economic growth, and global developments.

What Is Dr. Sherry Cooper Saying About Canada’s Economy?

Dr. Sherry Cooper, Chief Economist for Dominion Lending Centres, recently shared her perspective on Canada’s economic outlook.

One of the encouraging observations is that Canada’s economy has demonstrated considerable resilience despite ongoing trade tensions with the United States.

Canada has experienced consecutive periods of positive trade growth and continues developing relationships with new trading partners.

However, there are still challenges.

Employment conditions have weakened, particularly for younger Canadians entering the workforce, and uncertainty surrounding international trade continues to influence economic confidence.

When it comes to housing, Dr. Cooper also highlighted an interesting shift in mortgage preferences.

More Canadians are choosing mortgage terms shorter than five years.

This suggests borrowers are increasingly interested in maintaining flexibility rather than committing to longer mortgage terms during uncertain economic conditions.

And that brings us to an important question.

Should You Choose a Fixed or Variable Mortgage Rate Right Now?

This is probably one of the most common conversations I’m having with clients.

And my answer hasn’t changed.

The right mortgage isn’t necessarily the one with the lowest advertised rate. It’s the one that supports your financial situation, comfort level, and long-term goals.

Variable-rate mortgages have offered attractive opportunities for many borrowers, particularly those who secured lower rates before this latest increase.

Even with a 0.25% increase, some borrowers may still be benefiting from rates below comparable fixed-rate options.

But variable rates also come with uncertainty.

For example, on a $500,000 mortgage amortized over 25 years, a 0.25 percentage point rate increase would translate to approximately $70 more per month if the payment were recalculated at the higher rate.

For borrowers with static-payment variable mortgages, the monthly payment may remain unchanged while more of that payment goes toward interest and less toward principal.

That’s an important distinction.

Fixed-rate mortgages, on the other hand, offer payment stability and protection against further rate increases during the mortgage term.

Neither option is automatically better.

The key is understanding the numbers, the risks, and how each option fits your circumstances.

Is Now Still a Good Time to Buy a Home in British Columbia?

There is another side to this conversation that often gets overlooked.

While higher interest rates can affect affordability, they can also influence buyer competition and seller expectations.

Dr. Cooper noted that home prices have remained relatively flat in parts of the Canadian market, while new listings have declined.

For qualified buyers, certain market conditions may create opportunities to negotiate more favourable purchase terms.

Consider this:

A slightly higher mortgage rate doesn’t necessarily eliminate the opportunity to purchase a property at a competitive price.

And unlike your purchase price, your mortgage rate can potentially change over time through renewal, refinancing, or other available options.

Of course, purchasing a home should never be based solely on the expectation that interest rates will eventually decline.

Your mortgage payment needs to be affordable today, with room in your budget for unexpected expenses or future rate changes.

For buyers in Coquitlam, Port Coquitlam, Port Moody, Vancouver, and throughout British Columbia, understanding your purchasing power before entering the market remains one of the most valuable steps you can take.

What Should You Do If You Already Have a Variable-Rate Mortgage?

First, don’t make a rushed decision based on one Bank of Canada announcement.

If you currently have a variable-rate mortgage, there are a few things worth reviewing:

  1. Your current rate. How does it compare with the fixed-rate options available to you?
  2. Your monthly payment. Will your payment increase, or will the allocation between interest and principal change?
  3. Your remaining mortgage term. How much time do you have before renewal?
  4. Your financial flexibility. Could your budget comfortably accommodate additional increases?
  5. Your long-term plans. Are you considering selling, refinancing, or making changes to your property?

One thing I always encourage clients to understand is that locking into a fixed rate isn’t automatically the safest financial decision.

It provides certainty, but that certainty can come at a cost.

Depending on your mortgage terms, locking in may mean accepting a higher interest rate, and breaking a fixed-rate mortgage later can sometimes result in substantial penalties.

Before making that decision, let’s review the numbers together.

What Happens Next With Canadian Interest Rates?

The reality is that nobody can predict with certainty where interest rates will go over the next 12 months.

The Bank of Canada will continue evaluating inflation, employment, consumer spending, energy prices, and international economic conditions.

Additional rate increases are possible if inflationary pressures persist.

On the other hand, weaker economic growth or declining inflation could eventually create conditions for rates to stabilize or decrease.

That’s why I believe mortgage decisions should be built around a strategy rather than predictions.

A good mortgage strategy considers where you are today, where you want to be in three to five years, and how to protect your financial flexibility along the way.

My Final Thoughts

Interest rate announcements tend to generate attention, and understandably so. Your mortgage is likely one of your largest financial commitments.

But one rate increase doesn’t tell the entire story.

Whether you’re purchasing your first home, renewing your mortgage, refinancing, or simply wondering if your current mortgage still makes sense, this is an opportunity to review your options rather than react out of fear.

You don’t need to predict the market perfectly. You need a mortgage strategy that works for you.

If you’re unsure how this latest Bank of Canada announcement affects your mortgage, I’m happy to walk through the numbers with you so you can make an informed decision.

Let’s have a conversation about your mortgage strategy.

Book a Mortgage Strategy Call

Livian Smith is a licensed mortgage broker serving clients throughout British Columbia, including Coquitlam, Port Coquitlam, Port Moody, Vancouver, and surrounding communities.

Economic commentary informed by the October 28, 2026 Bank of Canada announcement and insights shared by Dr. Sherry Cooper, Chief Economist at Dominion Lending Centres.

This article is intended for general educational purposes. Mortgage rates, payment changes, product availability, and lending options depend on individual circumstances and lender terms. All financing is subject to lender approval.
2 Sep

No Rate Cut Today. Don’t Panic. Here’s What Actually Matters.

General

Posted by: Livian Smith

Well… the Bank of Canada made its decision.

And if you were waiting for another rate cut before making your next move, you didn’t get one.

Today, September 2, the Bank of Canada held its overnight rate at 2.25%.

Cue the headlines.

But before you decide this is “bad news” for mortgages, homebuyers or the housing market, there’s a lot more happening underneath that 2.25% number.

And some of it is actually pretty encouraging.

Why Did the Bank Hold?

Canada’s economy has been showing more life.

GDP grew 3.3% in the second quarter after a very weak first quarter. Consumer spending strengthened, employment conditions improved and even housing activity started to rebound.

That’s good news.

The problem?

Inflation isn’t quite cooperating.

Headline inflation has been hovering around 3%, largely because gasoline prices remain high. Add ongoing conflict in the Middle East, higher oil prices, new U.S. tariffs and Canadian counter-tariffs, and the Bank has some very real inflation risks to watch.

So rather than cutting rates today, they chose to sit tight.

But Here’s the Part Mortgage Holders Need to Understand

A Bank of Canada announcement does not mean every mortgage rate just stayed exactly where it was.

This is one of the biggest misunderstandings I see.

The Bank of Canada’s overnight rate directly influences prime rate, which affects variable-rate mortgages and lines of credit.

Fixed mortgage rates are influenced much more heavily by the bond market.

And Canadian long-term bond yields have actually moved up since July.

Translation?

Waiting for the Bank of Canada to cut its rate doesn’t necessarily mean the fixed mortgage rate you’re watching will be cheaper later.

The two don’t move in lockstep.

So… Should You Wait?

This is where I give the same answer I give my clients all the time:

It depends.

I know. Annoying. 😂

But your mortgage strategy shouldn’t be based on trying to perfectly predict the Bank of Canada.

Are you buying?

Renewing?

Refinancing?

Carrying expensive debt?

Thinking about moving?

Considering a variable mortgage?

Those are completely different conversations.

The question isn’t simply:

“Are rates going down?”

The better question is:

“What makes sense for me based on where rates, the market and my finances are today?”

October 28 Is the Next Big Date

The Bank of Canada’s next scheduled rate announcement is October 28, 2026.

Could things change by then?

Absolutely.

The Bank itself acknowledged that uncertainty remains high.

But spending the next eight weeks sitting on the sidelines hoping someone in Ottawa makes your financial decision easier isn’t much of a strategy.

Get the information.

Run the numbers.

Understand your options.

Then make the decision that’s right for you.

Because sometimes waiting saves you money.

And sometimes waiting costs you money.

Knowing the difference is where good mortgage advice comes in.

Have questions about what today’s Bank of Canada decision means for your mortgage? Our doors are always open.

Livian Smith
Mortgage Broker

6 Aug

Purchase Plus Improvements: Buy the Home You Want, Then Make It Perfect

General

Posted by: Livian Smith

Have you ever walked through a home and thought,

“I love everything about it… except the kitchen.”

Or maybe the bathrooms are dated, the flooring needs replacing, or it needs a new roof.

Most buyers assume they have two choices:

• Buy the home and somehow come up with thousands of dollars after possession to renovate.
• Walk away and keep searching.

But there’s actually a third option that many Canadians don’t know about.

What is a Purchase Plus Improvements Mortgage?

A Purchase Plus Improvements mortgage allows you to finance eligible renovations into your mortgage when you purchase a home.

While this program is most commonly used with insured mortgages (less than 20% down), many lenders also offer Purchase Plus Improvements options for conventional mortgages with 20% or more down payment.

Instead of paying for renovations entirely out of pocket, your lender can advance the renovation funds after the work has been completed and verified, allowing you to spread the cost over the life of your mortgage.

For many buyers, this can make purchasing a home much more affordable.

Who is it for?

This program can be a great option for:

• First-time home buyers
• Buyers with less than 20% down payment
• Buyers putting 20% or more down
• Buyers wanting cosmetic updates
• Buyers purchasing homes that need repairs before moving in
• Buyers looking to increase the value of their property

What types of renovations can be included?

Every lender has slightly different guidelines, but common improvements include:

• New kitchens
• Bathroom renovations
• Flooring
• Windows and doors
• Roofing
• Heating systems
• Electrical upgrades
• Plumbing
• Septic systems
• Cosmetic renovations
• Energy-efficient upgrades

How does it work?

The process is straightforward, but planning ahead is essential.

  1. You find a home and have an accepted offer.
  2. You obtain written quotes from licensed contractors.
  3. The contractor quotes are submitted along with your accepted offer and mortgage application before the lender issues the mortgage commitment.
  4. The lender reviews and approves both the mortgage and the proposed improvements.
  5. Your mortgage closes.
  6. The renovations are completed.
  7. Once the work has been verified, the lender releases the approved renovation funds.

In many cases, homeowners pay the contractor and are reimbursed once the work has been completed.

However, some contractors are willing to accept a small deposit upfront and receive the balance directly from the lawyer once the renovations have been completed and the lender has authorized the release of funds. This arrangement is made directly between you and your contractor and should be discussed before the work begins.

Why buyers love this program

Instead of competing for the perfectly renovated home, which often commands a premium price, you can purchase a home with great potential and customize it to suit your tastes.

This can allow you to:

• Increase the property’s value
• Personalize your home
• Finance eligible improvements through your mortgage
• Preserve more of your savings after possession

A real-world example

Let’s say you purchase a home for $700,000.

The kitchen is outdated and the flooring needs replacing. Your contractor provides quotes totaling $35,000.

Those quotes are submitted with your accepted offer and mortgage application. The lender approves the renovation budget as part of your financing.

After your purchase closes and the renovations are completed, the lender releases the approved funds according to its guidelines.

Instead of needing an extra $35,000 in cash after moving in, you’ve been able to include the renovation costs as part of your overall financing strategy.

Is it right for everyone?

Not necessarily.

Purchase Plus Improvements mortgages have lender and insurer guidelines that must be followed, including:

• Approved contractor quotes submitted before final mortgage approval
• Eligible renovations
• Maximum improvement limits
• Required documentation
• Completion deadlines for the renovations

Because every lender has different requirements, it’s important to discuss this option before removing subjects on your purchase.

Final Thoughts

Some of the best opportunities on the market are homes that need a little work.

If you’ve been scrolling past listings because they’re “not quite right,” a Purchase Plus Improvements mortgage could open up far more options than you realized.

The key is planning ahead. The renovation quotes and financing strategy need to be in place early in the mortgage process, so having the right advice from the beginning can make all the difference.

If you’re considering buying a home that needs updating, let’s talk before you write your offer. There may be a financing solution that helps you purchase the home you want while creating the home you’ll love.

Our door is always open.

16 Jul

Before You Read Another Interest Rate Headline, Read This.

General

Posted by: Livian Smith

The Bank of Canada made its interest rate announcement today.

Within minutes, the internet was flooded with opinions.

Some people are convinced rates are coming down.

Others are certain they’re headed back up.

Everyone seems to have a prediction.

Here’s the thing.

Very few of those predictions will help you decide whether you should buy a home.

That’s the conversation worth having.


So… What Happened Today?

The Bank of Canada decided to hold its overnight lending rate at 2.25%.

If you’re wondering whether that’s good news or bad news, the answer is…

It depends.

And that’s probably not the answer you were hoping for.


The Biggest Mistake I See

I’ve been in the mortgage industry for more than 20 years.

One thing hasn’t changed.

People spend an incredible amount of time trying to predict the market.

They wait for lower rates.

They wait for lower home prices.

They wait for “the perfect time.”

The problem?

The perfect time has a funny way of never showing up.


Let Me Ask You a Question

If the Bank of Canada had lowered rates by a quarter of a percent today…

Would you suddenly be ready to buy a home?

If the answer is no, then today’s announcement wasn’t really what was holding you back.

Because buying a home has never been about one interest rate announcement.

It’s about your financial picture.

Your goals.

Your timeline.

Your comfort level.

Those things matter far more than trying to predict the next Bank of Canada decision.


Headlines Don’t Buy Homes

I know that’s not as exciting as a bold prediction.

But it’s true.

Every rate announcement creates another round of headlines.

“Rates are about to fall.”

“Now is the time to buy.”

“Wait another six months.”

The reality?

Nobody knows exactly what the future holds.

Not me.

Not the media.

Not the person arguing in the Facebook comments.

Anyone who tells you they know exactly where rates are going is making an educated guess.

Some guesses turn out to be right.

Many don’t.


Here’s What You Can Control

You can’t control inflation.

You can’t control the Bank of Canada.

You can’t control global events.

But you can control your preparation.

You can improve your credit.

You can reduce debt.

You can increase your savings.

You can understand what you qualify for before you start shopping.

You can build a plan.

Those are the things that move you closer to homeownership.


The Difference Between Hope and a Plan

Over the years, I’ve watched people make two very different decisions.

Some waited because they hoped something would change.

Others made a plan.

Sometimes they bought right away.

Sometimes they waited.

But when they did wait, it was because it fit their strategy, not because they were waiting for a headline to tell them what to do.

That’s a very different mindset.

Hope is important.

But hope is not a strategy.


So What Does Today’s Announcement Mean?

For some people…

Not much.

For others…

It might be the nudge they needed to start asking questions.

The most important question isn’t:

“What did the Bank of Canada do today?”

It’s this:


“What should I do based on my own financial situation?”

That’s the conversation that actually matters.

If you’re wondering whether you’re ready to buy, refinance, renew, or simply want to understand your options, let’s talk.

No pressure.

No predictions.

Just a plan that’s built around you.

6 Jul

The Hidden Cost of “Once-in-a-Lifetime” Spending

General

Posted by: Livian Smith


“It’s once in a lifetime.”

I’ve heard that phrase a lot lately.

And to be fair… for many people, the FIFA World Cup in Canada really is a once-in-a-lifetime event.

The atmosphere is electric.

The memories are unforgettable.

The experience is incredible.

So this isn’t a blog telling you not to go.

It’s a blog asking a different question.

What are we giving up without realizing it?

We’re Living in a Time of Contradictions

Every day I hear people say:

“Homes are impossible to afford.”

“The cost of living is out of control.”

“I’ll never be able to buy a home.”

Then, in the same week, some of those same people are financing vacations, carrying credit card balances at nearly 20% interest, buying $500 concert tickets, or spending thousands on FIFA.

Again…

There’s nothing wrong with enjoying life.

The issue isn’t the purchase.

It’s whether the purchase is aligned with your long-term goals.

Small Decisions Become Big Numbers

Let’s put things into perspective.

A family of four attending a World Cup match could easily spend:

  • Tickets
  • Flights or fuel
  • Hotel
  • Food
  • Merchandise

It’s not difficult to spend $5,000–$10,000 over a weekend.

That’s a meaningful amount of money.

Could it have been used differently?

Maybe.

Could it become part of a down payment?

Possibly.

Could it pay off a high-interest credit card?

Absolutely.

Does that mean you shouldn’t spend it?

Not necessarily.

But it’s worth asking yourself whether you’re making the decision intentionally—or emotionally.

The Real Cost Isn’t the Ticket

The real cost isn’t the FIFA ticket.

It’s the interest that comes afterward.

It’s the credit card balance that quietly grows month after month.

It’s convincing yourself that homeownership isn’t possible because everything is expensive, while unknowingly making choices that move the goalposts farther away.

Those decisions rarely happen all at once.

They happen one swipe at a time.

What If Homeownership Is Closer Than You Think?

One of the biggest surprises I see as a mortgage broker is how many people assume they can’t buy a home.

They’ve never asked.

They’ve never run the numbers.

They’ve simply assumed.

Sometimes they’re right.

But quite often…

They’re pleasantly surprised.

We’ve helped clients realize they were much closer than they thought because they finally looked at the numbers instead of the headlines.

Spend With Purpose

Life isn’t meant to be lived waiting for “someday.”

Go to the concert.

Travel.

Watch the match.

Celebrate with family.

Create memories.

But do it because you’ve made a conscious choice—not because you haven’t taken five minutes to understand what those choices mean for your future.

Financial freedom isn’t built by never spending money.

It’s built by spending it on purpose.

Before You Decide You Can’t…

If you’ve been telling yourself that homeownership is out of reach, I’d encourage you to challenge that assumption.

Let’s have a conversation.

No pressure.

No obligation.

Just real numbers and honest advice.

You might discover that your dream home is closer than you think.

And if not?

At least you’ll have a plan to get there.

Because the best financial decisions aren’t made based on fear.

They’re made with information.


Livian Smith
Mortgage Broker | Advice for Life

Helping Canadians make informed mortgage decisions—one conversation at a time.

29 Jun

Are You Leaving $2,000 a Month on the Table?

General

Posted by: Livian Smith

Let’s talk about something that might sting a little.

When was the last time you reviewed your mortgage?

Not your Netflix subscription.

Not your cell phone plan.

Not whether you’re paying too much for strawberries these days.

Your mortgage.

For most Canadians, their mortgage is the single largest financial commitment they’ll ever have, yet many people sign the paperwork and don’t think about it again until renewal time.

That’s a bit like buying a car and never changing the oil.

“But My Mortgage Is Fine…”

Maybe.

Maybe not.

Over the last year, I’ve reviewed mortgages for homeowners who thought everything was working perfectly, only to discover opportunities to save hundreds or even thousands of dollars every month.

Sometimes it’s because rates have changed.

Sometimes it’s because life has changed.

And sometimes it’s because nobody has looked at their mortgage strategy in years.

Your Mortgage Should Evolve With Your Life

Think about where you were three years ago.

Different income?

Different goals?

Different family situation?

Different debt levels?

Maybe you’ve received a raise.

Maybe you’ve started a family.

Maybe you’ve accumulated some high-interest debt.

Maybe you’re planning renovations.

Maybe you’re thinking about buying a rental property.

The mortgage that made sense then may not be the mortgage strategy that makes sense now.

Real Savings Are Happening

A mortgage review isn’t about finding a lower rate just for the sake of finding a lower rate.

It’s about looking at the whole picture.

We’ve helped clients:

• Reduce monthly payments

• Consolidate high-interest debt

• Improve cash flow

• Create a plan to become mortgage-free sooner

• Position themselves for future home purchases

In some cases, homeowners have improved their monthly cash flow by over $2,000 per month.

Not because someone waved a magic wand.

Because they finally reviewed a mortgage that hadn’t been looked at in years.

The Cost of Doing Nothing

Here’s the uncomfortable truth.

Doing nothing is still a decision.

Every month that passes without reviewing your mortgage strategy is another month you could be missing opportunities to improve your financial position.

Maybe there aren’t any changes to make.

That’s great.

At least you’ll know.

But if there are opportunities available, wouldn’t you rather find out now instead of years from now?

The Good News

A mortgage review doesn’t obligate you to make any changes.

There is no pressure.

No commitment.

No awkward sales pitch.

Just a conversation about where you are today and whether your mortgage is still helping you achieve your goals.

Sometimes the best outcome is confirming you’re already in a great position.

Sometimes it’s discovering opportunities you didn’t even know existed.

Let’s Find Out

If it’s been more than a year since you’ve reviewed your mortgage, or if your life has changed significantly since you got it, it might be time for a second look.

Because if there is an extra $500, $1,000, or even $2,000 hiding in your monthly budget, wouldn’t you rather keep it than give it away?

And if everything looks perfect?

You can go back to worrying about the price of strawberries.


Livian Smith
Mortgage Broker | Advice for Life

Ready for a complimentary mortgage review?

Head over to LivianSmith.ca to learn more and book a time to chat.

23 Jun

Housing Is Finally Acting Like It Took a Deep Breath

General

Posted by: Livian Smith


Now for some news that doesn’t make us want to lie down in the Costco parking lot.

Housing costs continued to cool in May.

Mortgage interest costs actually declined slightly compared to last year.

Rent inflation also eased to its slowest pace since early 2022.

In other words, after spending the last few years behaving like an unsupervised toddler who found a drum set and an energy drink, housing costs are finally calming down.

For homeowners and future buyers, that’s encouraging news.

It’s the financial equivalent of hearing, “We’re all good here.”

So… Are Interest Rates Going Up Again?
I know.

You didn’t read 800 words about inflation because you’re passionate about economic indicators.

You want the answer to one question:

“Are rates going up again?”

According to Dr. Sherry Cooper, probably not.

Her expectation is that the Bank of Canada will remain on hold through the rest of 2026.

Which is economist language for:

“Everybody keep your hands and feet inside the ride.”

The inflation numbers the Bank really pays attention to are still behaving themselves.

Nobody at the Bank of Canada appears to be running through the hallways screaming into a clipboard.

What Does This Mean for You?
It means you can stop checking mortgage rates every time you open your phone.

At least for now.

The reality is that most Canadians aren’t being crushed by one giant expense.

They’re being nibbled to death by ducks.

Gas is up.

Groceries are up.

Insurance is up.

Your streaming subscriptions somehow multiplied while you weren’t looking.

And every trip to Costco starts with:

“I’m just grabbing one thing.”

Which is adorable.

Twenty minutes later you’re wheeling out a kayak, a flat of sparkling water, and enough snacks to survive a minor apocalypse.

That’s why reviewing your finances matters.

Not because something is wrong.

But because small leaks become big leaks.

I’ve reviewed mortgages for clients who were convinced everything was fine, only to discover opportunities that could save them hundreds or even thousands of dollars each month.

And unlike tomatoes, mortgage savings don’t suddenly increase by 45%.

My Take
The inflation headlines are giving major “we need to talk” energy.

Terrifying at first.

Usually less dramatic once you know the full story.

Yes, inflation moved higher.

Yes, groceries continue to test both our patience and our budgets.

And yes, tomatoes have fully entered their celebrity era and now require their own security detail.

But beneath the scary headlines, the bigger picture remains relatively stable.

Housing costs are easing.

Core inflation remains contained.

And according to Dr. Sherry Cooper, the Bank of Canada appears comfortable staying right where it is.

So before you cancel your vacation, build a bunker, or start growing tomatoes in your backyard as a retirement strategy, take a breath.

The economy isn’t perfect.

But it’s also not on fire.

Unlike the price of produce.

16 Jun

A Buyer’s Market Does Not Mean Buying Feels Easy

General

Posted by: Livian Smith

It has been a buyer’s market for a while now, but many buyers still feel stuck.

On paper, buyers have more choice, more time, and more negotiating power than they had during the peak frenzy. In Metro Vancouver, May 2026 sales were still below long-term seasonal averages, while active listings remained elevated compared to typical levels. That means buyers may have more selection than they have had in recent years. Greater Vancouver Realtors

But even with more inventory, buying a home still does not feel easy for many people.

Interest rates, qualification rules, monthly payments, closing costs, job uncertainty, and the fear of making the wrong decision are all very real. A buyer’s market does not magically make homes affordable. It simply changes the conversation.

Instead of rushing, competing, and removing conditions, buyers may now have more room to slow down and make better decisions.

That can mean:

Having time to review the property properly
Including financing and inspection conditions
Comparing more than one property
Negotiating on price, dates, or terms
Making decisions based on numbers, not panic

This is where mortgage strategy becomes so important.

A buyer’s market does not mean every buyer should buy. It means prepared buyers may have an opportunity to buy more strategically.

Before writing an offer, it is important to understand your full picture. That includes your down payment, closing costs, monthly payment comfort zone, credit, income, debt, and long-term goals.

The purchase price matters, but it is not the only number that matters.

A lower purchase price is helpful, but the real question is: can you comfortably carry the home, and does the mortgage strategy support your life?

Some buyers are waiting for rates to drop. Some are waiting for prices to drop further. Some are waiting because they are overwhelmed and do not know where to start.

There is nothing wrong with waiting if waiting is the right decision for you.

But if you are financially ready, this type of market may give you something that buyers did not always have over the last few years: breathing room.

More choice.
More time.
More ability to negotiate.
More opportunity to do proper due diligence.

The key is not to buy because the market says it is a good time.

The key is to buy when your numbers, your goals, and your comfort level all line up.

If you are wondering whether buying makes sense for you in today’s market, the best first step is not looking at listings. It is understanding your mortgage options, your monthly payment, and what you can comfortably afford.

Because a buyer’s market does not mean buying feels easy.

It means buying should be done with a plan.

Livian Smith
Dominion Lending Centres Producers West Financial

Our Door is Always Open!

10 Jun

Bank of Canada Holds Rates Steady: What It Means for Homeowners and Buyers

General

Posted by: Livian Smith

Bank of Canada Holds Rates Steady: What It Means for Homeowners and Buyers

The Bank of Canada has once again held its overnight lending rate at 2.25%, choosing to leave rates unchanged amid ongoing economic uncertainty.

For Canadians wondering whether rates are going up, down, or staying put, today’s announcement provides an important signal: the Bank believes current interest rates are appropriate for the economic conditions we’re facing right now.

Why Did the Bank Hold Rates?

Several factors are influencing the Bank’s decision:

• Inflation remains elevated at 2.8%, although core inflation has eased closer to the Bank’s 2% target.

• Ongoing geopolitical tensions continue to impact global markets, particularly energy prices.

• Trade uncertainty remains a concern as Canada, the United States, and Mexico continue negotiations surrounding the future of CUSMA.

• Economic growth in Canada has slowed, but recent data suggests the economy may be stabilizing after a weak start to the year.

The Bank of Canada is walking a careful line between controlling inflation and avoiding additional pressure on an already soft housing market.

What Does This Mean for Mortgage Rates?

While the Bank of Canada rate directly impacts variable-rate mortgages and lines of credit, fixed mortgage rates are influenced more by bond markets.

Recent increases in bond yields and global uncertainty have placed upward pressure on fixed mortgage rates. However, today’s announcement suggests the Bank is not currently eager to increase borrowing costs further.

The current expectation among economists is that rates will likely remain stable through the remainder of the year.

Could Rates Still Go Higher?

It’s possible, but it is not the base-case forecast.

If inflation begins rising more broadly across the economy, the Bank could consider future rate hikes. However, policymakers are also aware that higher rates could further weaken housing activity and affordability.

For now, the most likely scenario is a period of stability while the Bank monitors inflation, economic growth, and global developments.

What Should Homeowners and Buyers Be Doing?
Rather than trying to predict every rate announcement, focus on building a mortgage strategy that fits your long-term goals.

Questions worth considering include:

• Does a fixed or variable rate align better with your comfort level?
• Are you planning to move, refinance, or renew in the next few years?
• Could a different mortgage structure help you pay off your mortgage faster?
• How would your finances handle future rate fluctuations?

Every situation is different, which is why mortgage planning should go beyond simply finding the lowest rate.

Final Thoughts

The Bank of Canada continues to take a cautious approach. While inflation remains above target, economic growth has softened, and uncertainty surrounding global trade and energy markets remains high.

For now, rates appear likely to stay where they are, giving homeowners and buyers a chance to focus on long-term financial planning rather than reacting to every headline.

If you have questions about your mortgage, upcoming renewal, purchase plans, or whether a fixed or variable strategy makes sense for you, I’d be happy to help.

Source: Adapted from analysis by Dr. Sherry Cooper, Chief Economist, Dominion Lending Centres.

10 Jun

Canada’s Economy Sends a Strong Message: Recession Fears Put on Hold

General

Posted by: Livian Smith

Canada’s Economy Sends a Strong Message: Recession Fears Put on Hold

If you’ve been following the headlines lately, you’ve probably heard plenty of talk about a potential recession, economic uncertainty, tariffs, and rising costs. However, Canada’s latest employment report tells a very different story.

In May, the Canadian economy added an impressive 87,800 jobs, the strongest monthly gain since 2024. This significant jump surprised economists and suggests that Canada’s economy remains far more resilient than many expected.

What Happened?
Several key indicators showed strength across the country:

• Unemployment fell to 6.6%
• Full-time employment increased by 154,000 positions
• Employment gains were seen in construction, transportation, hospitality, manufacturing, and recreation
• British Columbia added approximately 25,000 jobs
• Ontario led the way with 42,000 new jobs
• Average wages increased by 3.0% compared to last year

Perhaps most encouraging was the broad-based nature of the gains. Employment increased among private sector workers, public sector workers, and across several major industries.

What Does This Mean for Interest Rates?

Whenever economic data comes in stronger than expected, one of the first questions people ask is:

“Will this cause the Bank of Canada to raise rates?”

While a strong labour market can create inflationary pressure, the answer is likely not anytime soon.

Canada’s housing market remains relatively fragile, and housing plays a much larger role in our economy than it does in the United States. Although inflation remains a concern, particularly with higher energy costs and ongoing global uncertainty, economists continue to believe that both the Bank of Canada and the U.S. Federal Reserve are unlikely to raise rates this year.

What This Means for Homeowners and Buyers

For Canadians considering buying a home, renewing a mortgage, or refinancing, this report is encouraging news.

A stronger job market generally means:

• Greater consumer confidence
• More stable household finances
• Improved economic growth
• Reduced recession concerns

At the same time, the Bank of Canada appears cautious about making any moves that could further pressure the housing market.

While no one can predict the future with certainty, today’s economic environment continues to support the view that interest rates are more likely to remain stable than move significantly higher in the near term.

My Take

As a mortgage broker, I always encourage clients to look beyond the headlines.

One economic report doesn’t tell the whole story, but this jobs report is an important reminder that Canada’s economy remains remarkably resilient despite higher borrowing costs, trade uncertainty, and global challenges.

If you’re wondering how today’s economic environment could impact your mortgage, renewal, refinance, or home-buying plans, let’s have a conversation. Every situation is unique, and the right strategy is about much more than simply chasing the lowest rate.

The goal is finding a mortgage that fits your life today while supporting your goals for the future.

Source: Dr. Sherry Cooper, Chief Economist, Dominion Lending Centres. This article is based on Dr. Cooper’s analysis of Canada’s May Labour Market Survey and related economic data.